We’ll sort the legwork
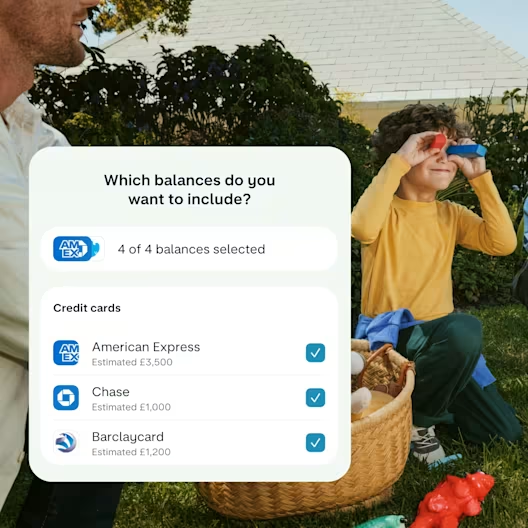
We work with ClearScore to track down what you owe and where – then pay your existing lenders directly on your behalf.
Personal loans

You'll need a Monzo current account to apply for a loan. Eligibility criteria and Ts&Cs apply. UK residents & 18+ years olds only. Missed payments may negatively impact credit scores. Our representative APR for loans of more than £10,000 and up to £35,000 is 10.0% APR. For loans up to £10,000 it's 23.0% APR.
Your current lenders might charge you a fee for paying off early and consolidating your debt might mean it takes longer to pay off. It could also cost more in total than you’re paying now.
Debt consolidation is the process of taking multiple debts – like credit cards and loans – and combining them into one new loan.
If you’ve got borrowing scattered across different places, it can feel mentally exhausting. Bringing it all together into one monthly payment can let you finally breathe again. Find out what you could borrow with our personal loans calculator.
Representative example: Borrowing £4,800.00, over 38 months, with 37 monthly repayments of £174.00 and one final payment of £149.81, at an annual interest rate of 20.9% (fixed), with a representative 23.0% APR, the total amount you'll repay is £6,587.81. Correct as at 12/11/2026.
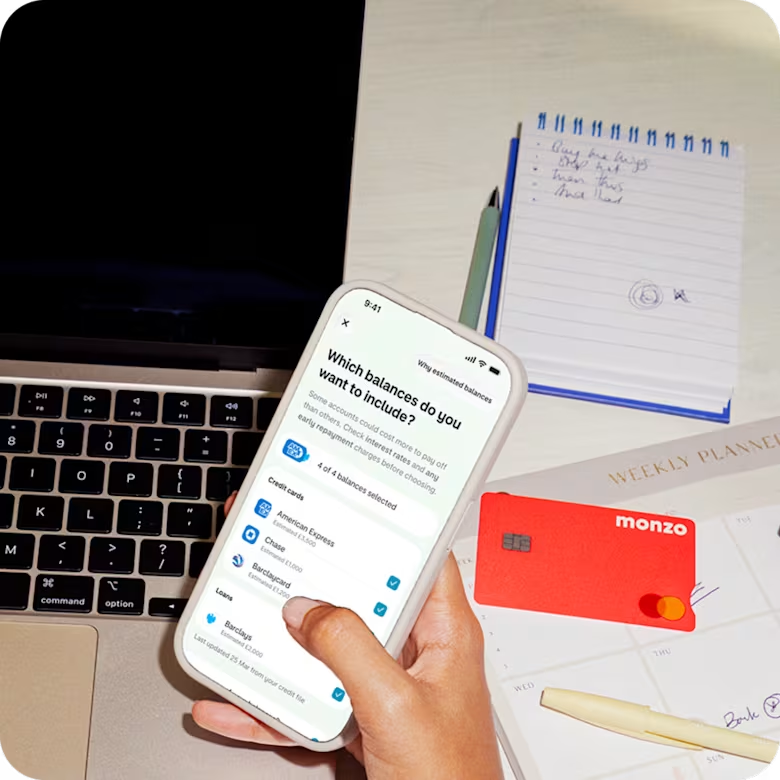
Bring what you owe into one clear Monzo loan. We automatically pay lenders for you, so you can focus on the future.
We work with ClearScore to track down what you owe and where – then pay your existing lenders directly on your behalf.
Instead of multiple due dates and different amounts to track, you get one payment and a clear end date.

Want to pay extra or clear the consolidation loan early? Go for it – straight from the Monzo app, with no fee.

Step 1
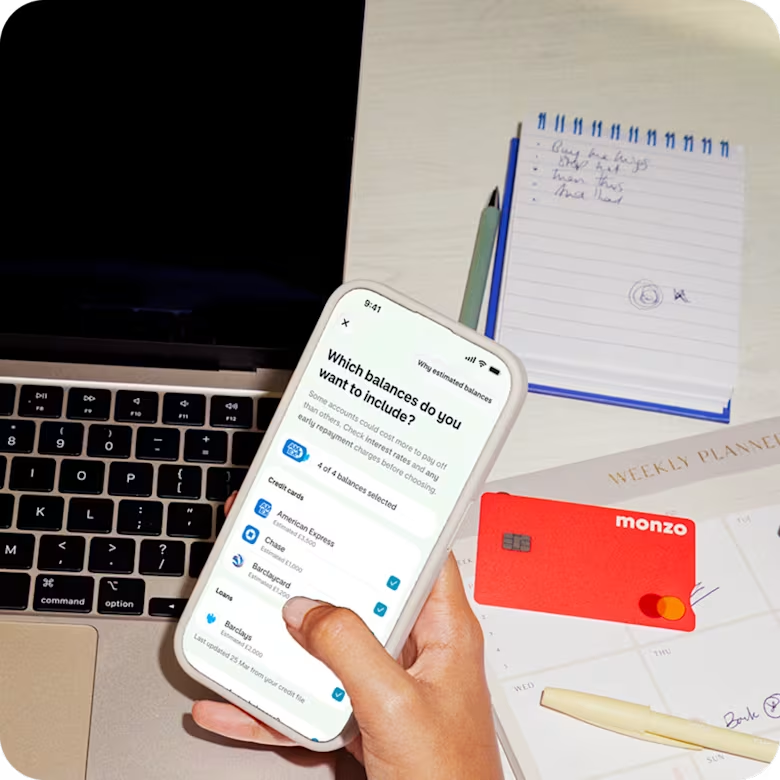
We find your balances
We find these from your credit file. Select your balances and decide how much to pay off.
Step 2
ClearScore pays your lenders
Usually within 1 working day.
Step 3
Start chipping away at your loan
You’ll have one monthly payment and a fixed end date. We'll tell you when your first payment's due.
You’ll need a Monzo current account to see if you’re eligible for a loan.
Instead of keeping track of various credit cards and loans, a debt consolidation loan helps you to pay them off with a single, manageable plan. It’s one loan that clears your scattered debts.
A debt consolidation loan rolls multiple existing balances into one single loan. Instead of managing different due dates and interest rates, you use the new loan to pay off your old credit cards and loans completely. You’re then left with one loan, one monthly payment and a fixed end date.
To do this, you apply for a loan that matches the total amount you currently owe. Once approved, you use the money to clear your existing balances to zero, essentially replacing them with your new loan.
A debt consolidation loan could be right for you if it simplifies things by rolling multiple types of borrowing into one monthly payment, especially if it lowers your overall interest rate. It works best if you have a stable income to cover the new repayments and you’re committed to not taking on any new credit cards or loans. However, if it extends your loan term, you might end up paying more in interest over the long run, so it's always worth checking the total cost before deciding.
When you apply for a debt consolidation loan, lenders will do a hard check on your credit file, which will cause your score to dip temporarily.
If you use the loan to pay off your old balances and keep making your new monthly repayments on time, your score should actually start to go up over time. It shows lenders you’re responsible and can manage your money well.
Just keep in mind that if you miss payments on the new loan, or keep spending on the credit cards you just cleared, this will impact your score.
A debt consolidation loan is when you borrow money to pay off all your current balances in one go. This leaves you with one monthly payment to keep track of.
A Debt Management Plan (DMP) isn’t a loan. Instead, a free debt charity helps you work out a realistic budget and negotiates with your lenders so you only pay what you can afford each month. They’ll also ask your lenders to pause interest. It’ll likely lower your credit score temporarily, but can be a huge help if you’re facing financial difficulties.
It’s up to you if you want to close any old credit cards after they’re paid off. Monzo doesn’t close them for you.
If you don’t need the card any more, closing it means you won’t spend on it in future and makes it easier to manage all your borrowing. However, closing an older account can sometimes lower your credit score.
You’ll need to consider which option best fits your goals.
You can make your monthly payment early, pay off a little extra or pay your loan in full anytime. We don’t charge a fee.
We’ve partnered with ClearScore to pay your lenders on your behalf. Once you’ve selected your balances, they’ll take care of the payments for you.
We’ll share the information you provide with ClearScore so they can find your balances, pay your lenders, and transfer any remaining loan amount directly into your Monzo account. They usually pay your lenders within 1 working day.
ClearScore uses bank-level encryption to help keep your information safe.